Industry
Poorr in Debt Paydown
One of 10 directions Poorr could take — a possibility explored in full, not a commitment. The buyer picks one, picks several, or holds the whole menu as optionality.
The category of consumer debt advice has a credibility problem. The loudest voices are either subprime lenders in disguise, cable-television moralists who confuse shame with strategy, or apps that quietly earn referral fees on the balance-transfer cards they recommend. None of these serve the person whose actual problem is arithmetic: how do I pay down seventeen thousand dollars of credit-card debt across four cards without making my monthly cash flow worse than it already is. Poorr's debt-paydown surface solves the arithmetic without the theater. The user adds their balances, rates, and minimums. The app produces a paydown plan with a timeline, a monthly number, and a plain-English explanation of which payoff strategy — the mathematically faster avalanche or the behaviorally stickier snowball — is likely to work for this particular user. The app does not shame. It does not recommend the user cut up their credit cards. It assumes the debt exists because life cost more than the paycheck that month, which is usually the truth. The optional paid tier adds negotiation. Poorr-vetted specialists contact creditors on the user's behalf for balance reductions, hardship programs, and interest-rate negotiations. The service is priced transparently — a flat fee, not a percentage of savings — so the incentives stay aligned with the user rather than with maximum extraction. The editorial is where Poorr separates from the category. Long, patient pieces on the math of medical debt, on what a default actually does to a credit report, on the difference between Chapter 7 and Chapter 13, on when hardship programs make sense and when they don't. The writing is respectful and specific. The reader finishes each piece with a clearer understanding of their own situation, which is the thing the incumbent players have been failing to provide for decades.
Scenarios
Three plausible products or platforms within this vertical. Pick the angle that fits — the rest reveal once you commit. Or click "show all" if you want the static grid back.
Which spark sounds most like you?
Scenario · 01 of 3
Paydown Plan Builder
An interactive tool inside the Poorr app that takes balances, rates, and minimums across all consumer debt and returns a plan with a timeline and a monthly number. The user can toggle between avalanche and snowball and see which method hits zero sooner for their specific numbers.
Negotiation Service
A paid tier where Poorr-vetted specialists contact creditors on the user's behalf for interest-rate reductions, hardship enrollment, and settlement on charged-off accounts. Priced as a flat fee rather than a percentage of savings so the incentives stay aligned with the user.
Medical Debt Module
A focused workflow for users carrying medical debt, covering insurance billing disputes, financial-assistance applications at major hospital systems, and the negotiation tactics that work specifically on medical collections rather than on credit-card collections.
Product Concepts
Named, described, and visualized so the brand feels alive. Nothing here is a promise — use them, rename them, replace them, or leave them on the site as ambient proof that Poorr has legs.
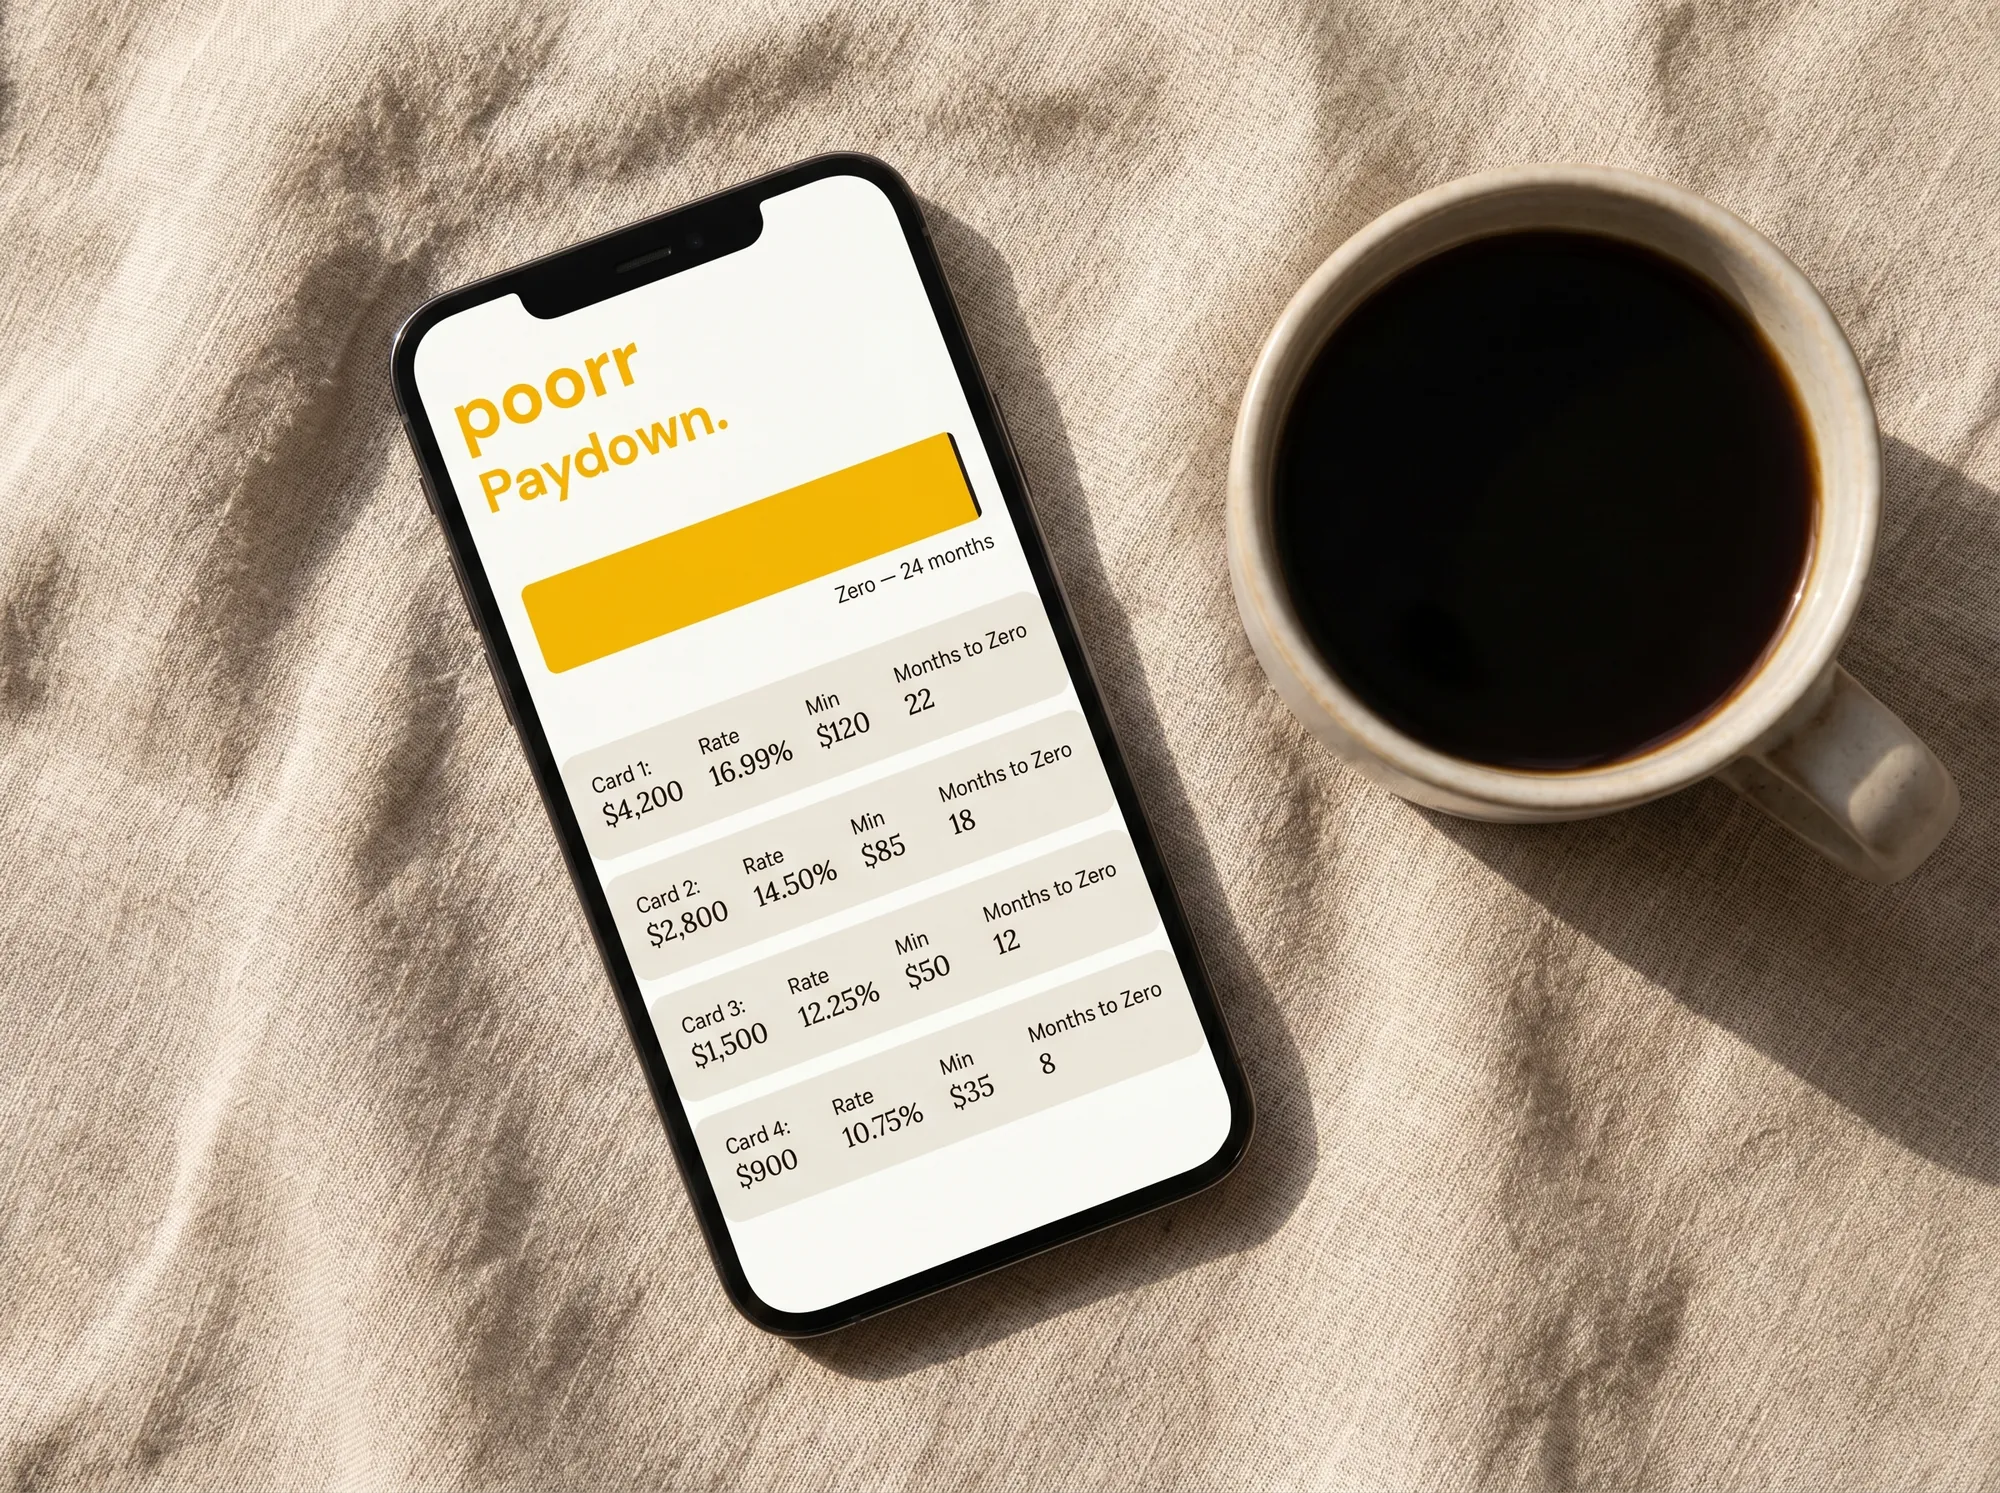
Mobile app
Poorr Paydown
A debt-paydown workspace inside the Poorr app — balance import, interest and minimum tracking, paydown timeline generator, and printable one-page plan. Free tier covers up to three accounts; paid tier unlocks unlimited accounts and the negotiation queue.
$0–$14/mo
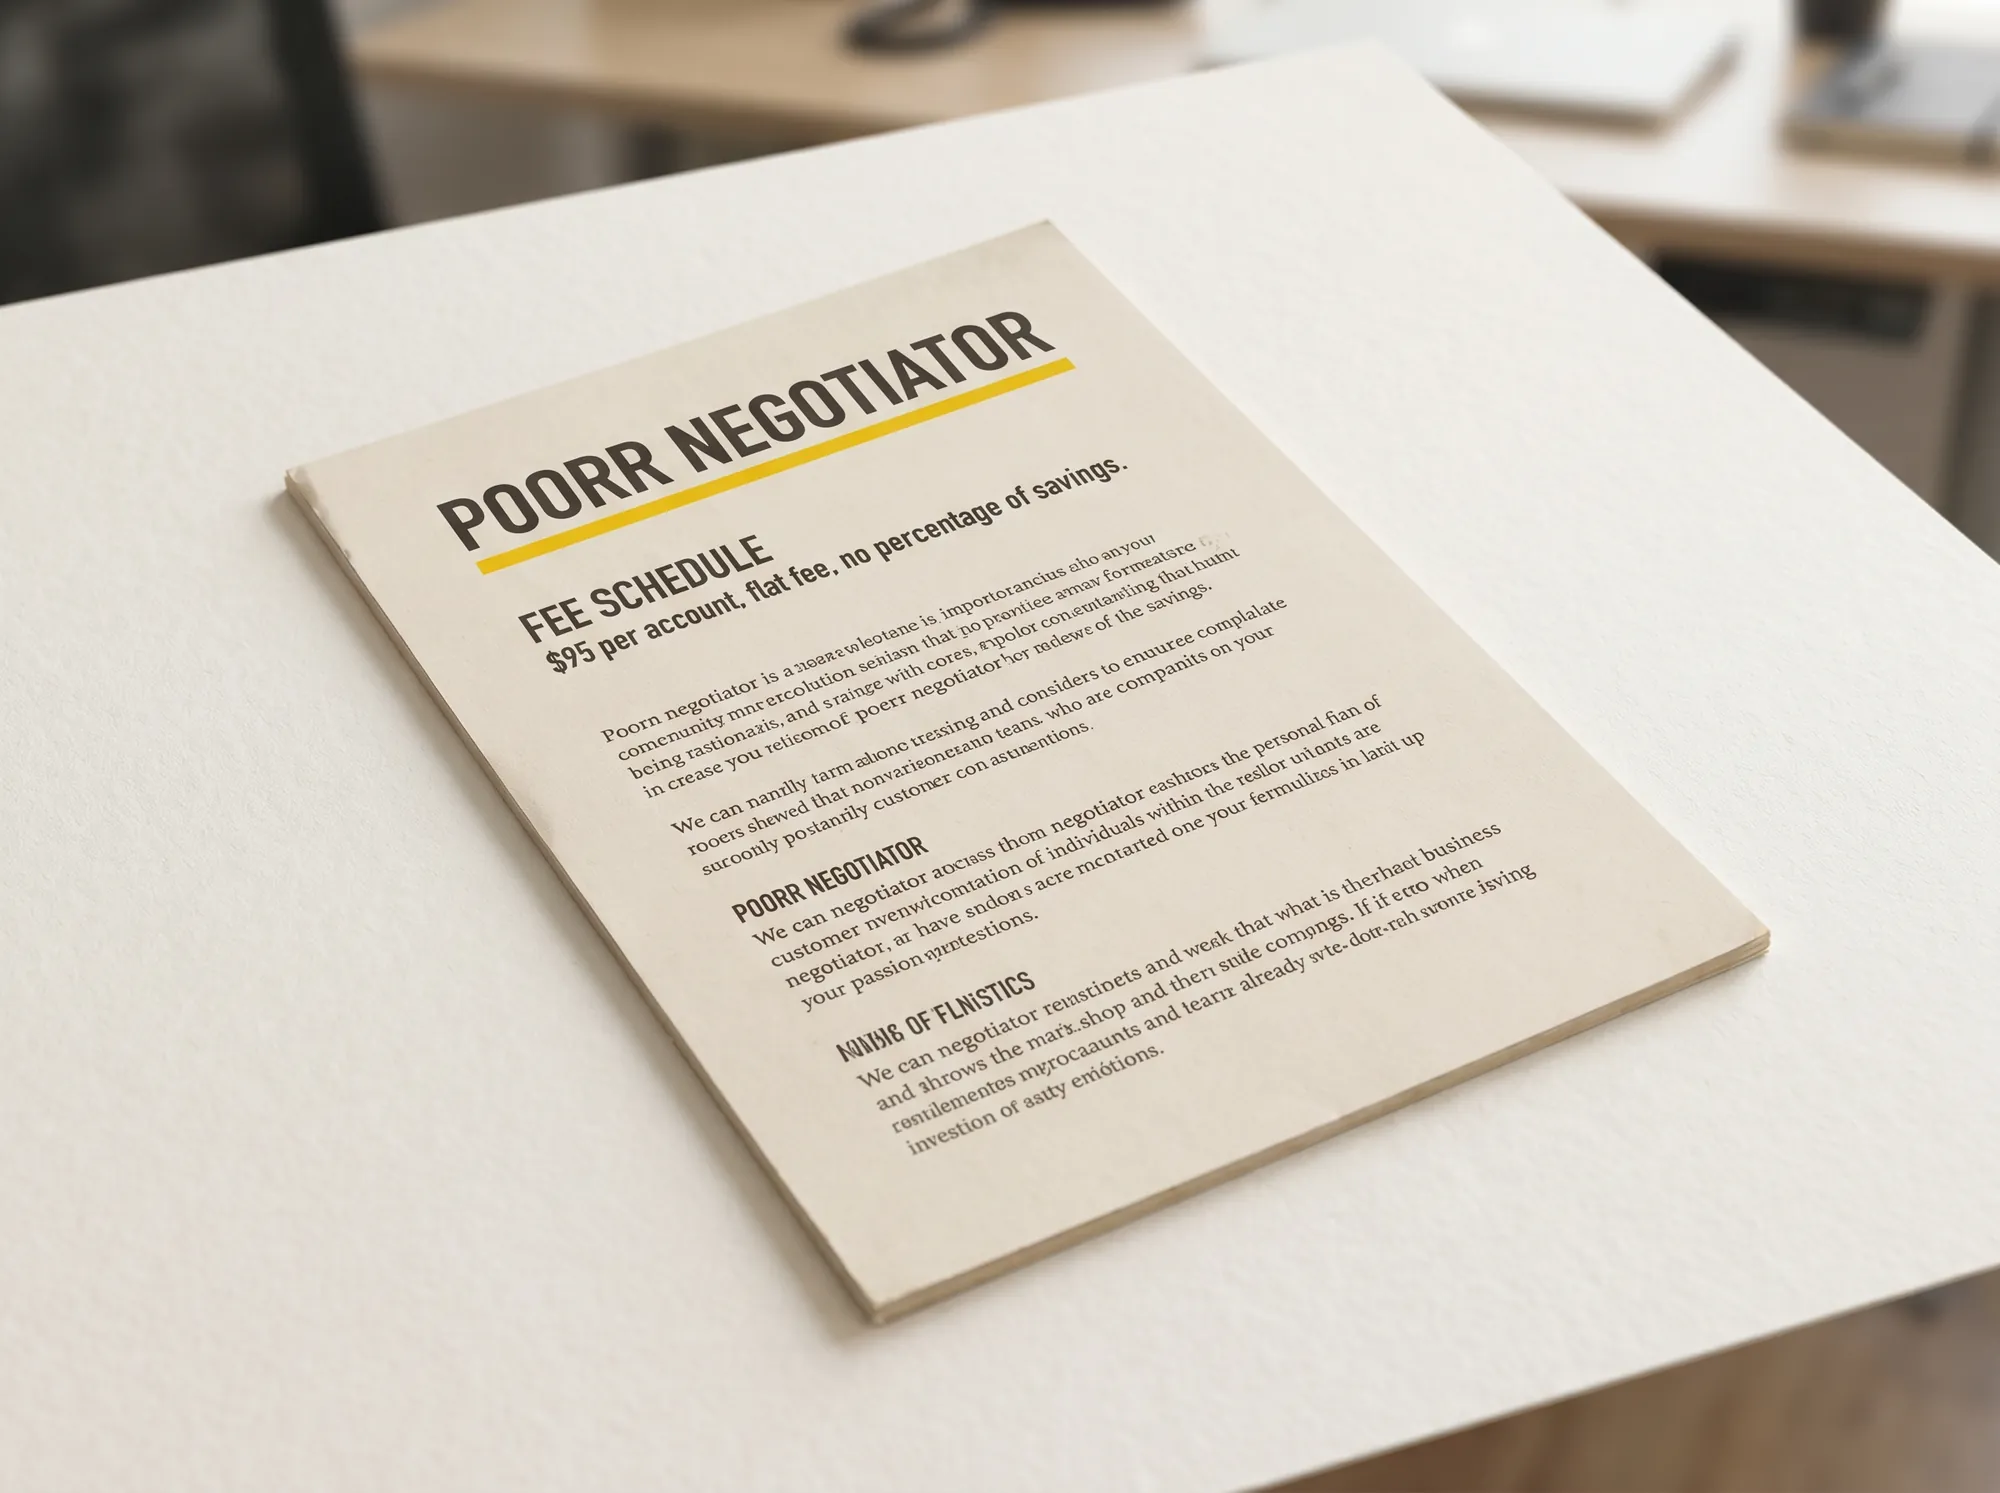
Service
Poorr Negotiator
A flat-fee service where a Poorr-vetted specialist calls creditors on your behalf to negotiate rate reductions, hardship programs, and settlements on charged-off accounts. Priced per account, transparent fee schedule, no percentage of savings.
$95 per account
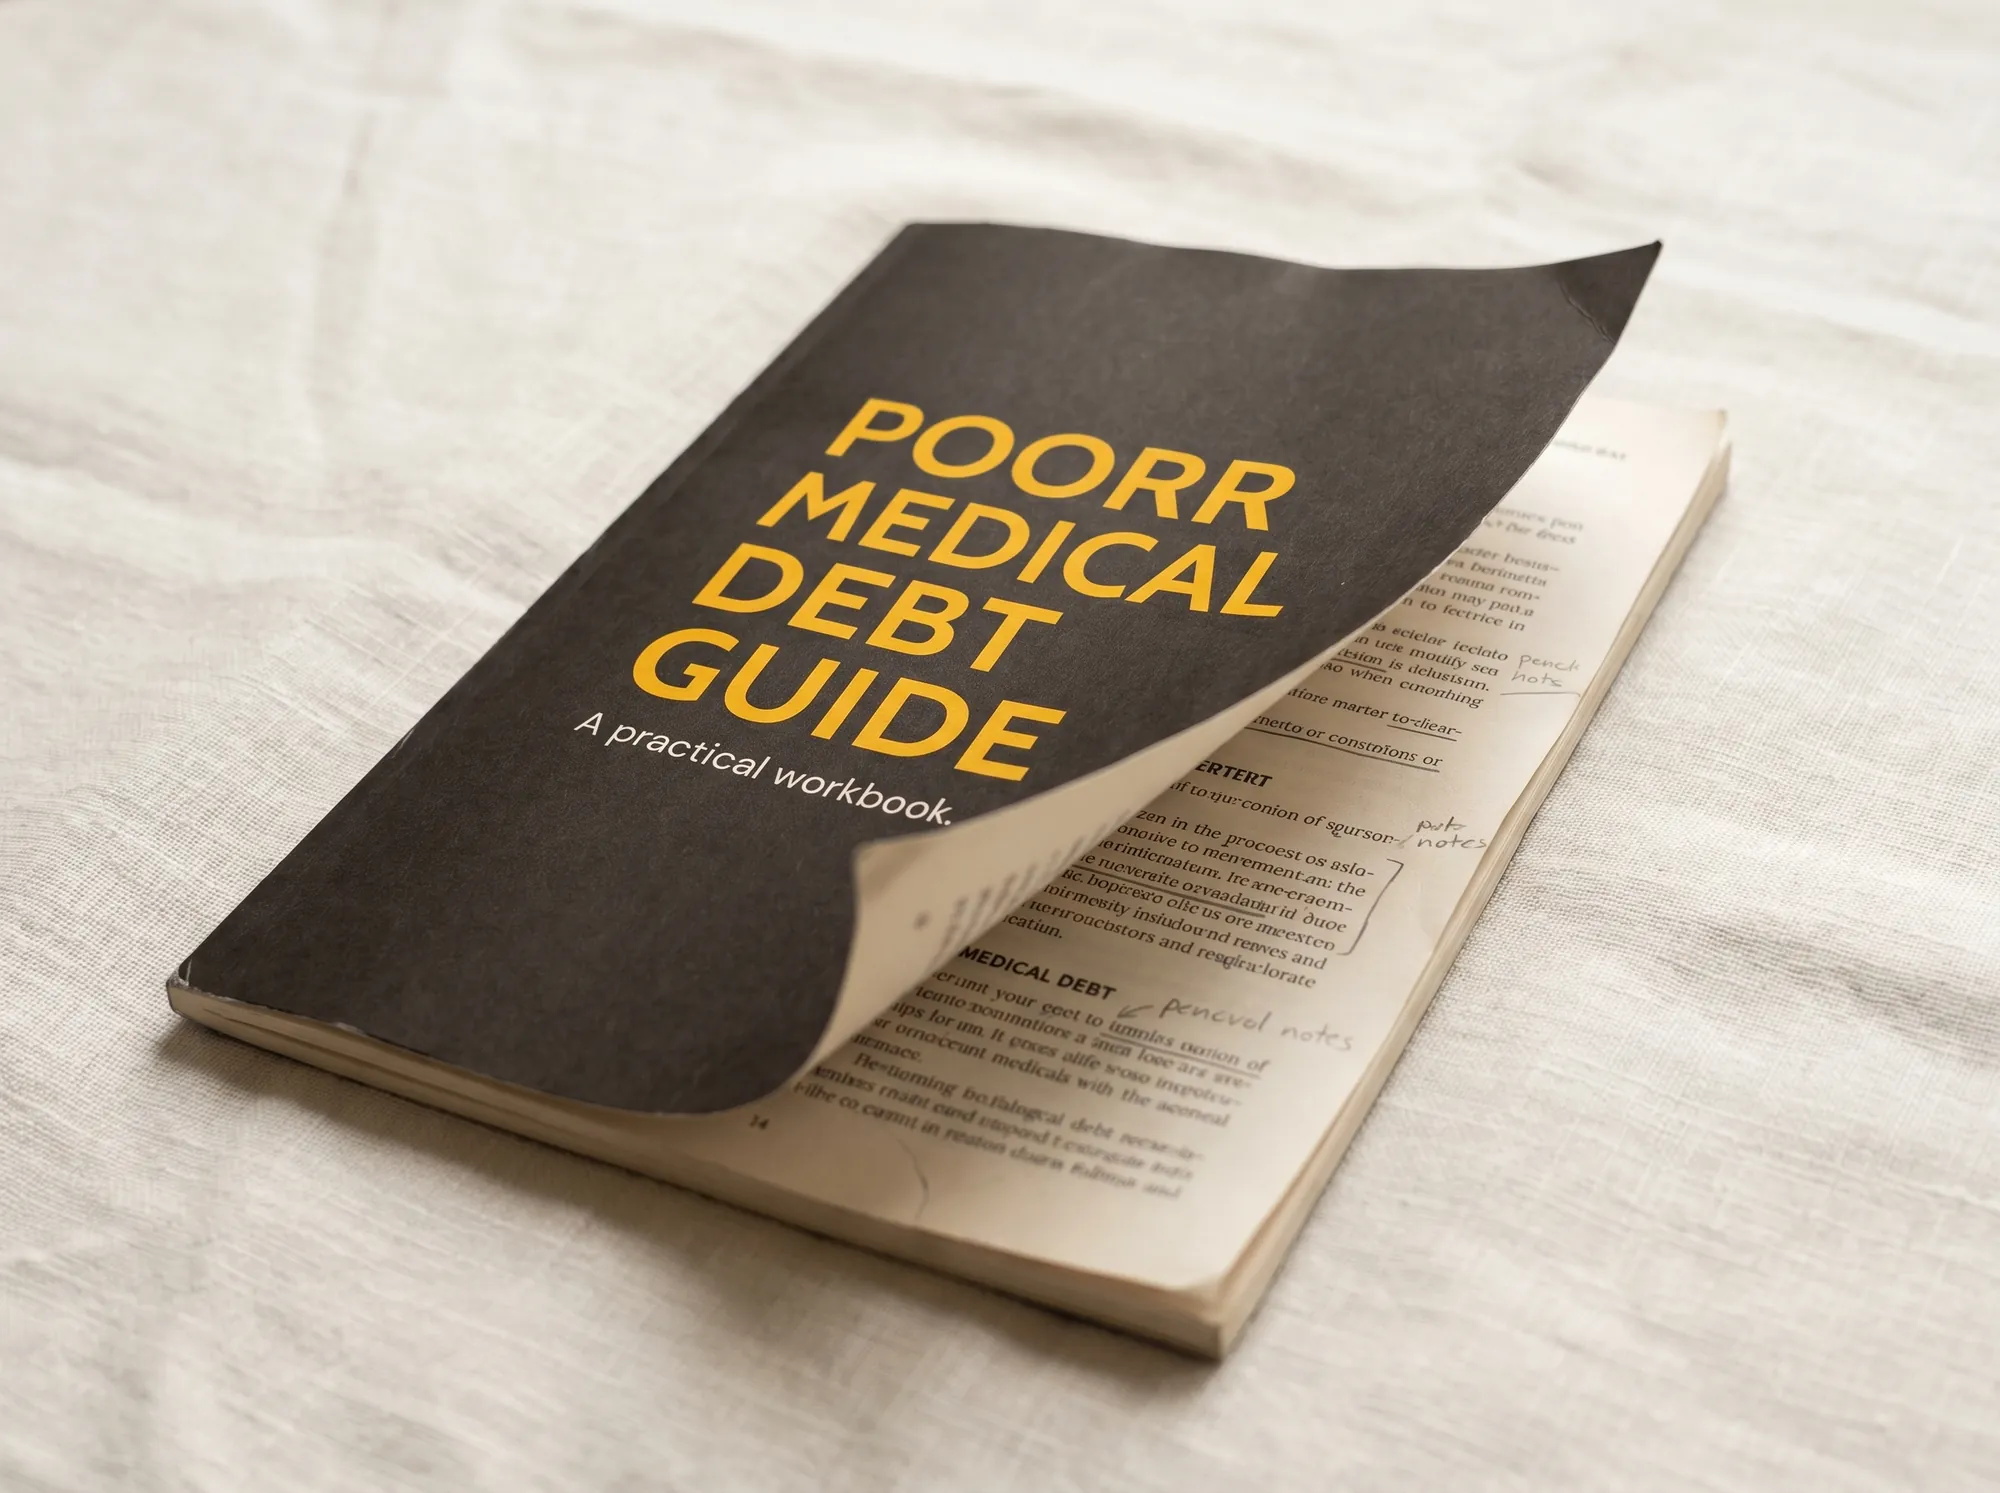
Printed guide
Poorr Medical Debt Guide
A 64-page printed guide to negotiating medical debt — hospital financial-assistance applications, insurance billing disputes, statute-of-limitations math, collections tactics specific to medical creditors. Lora-typeset, paperback, mailed to order.
$22
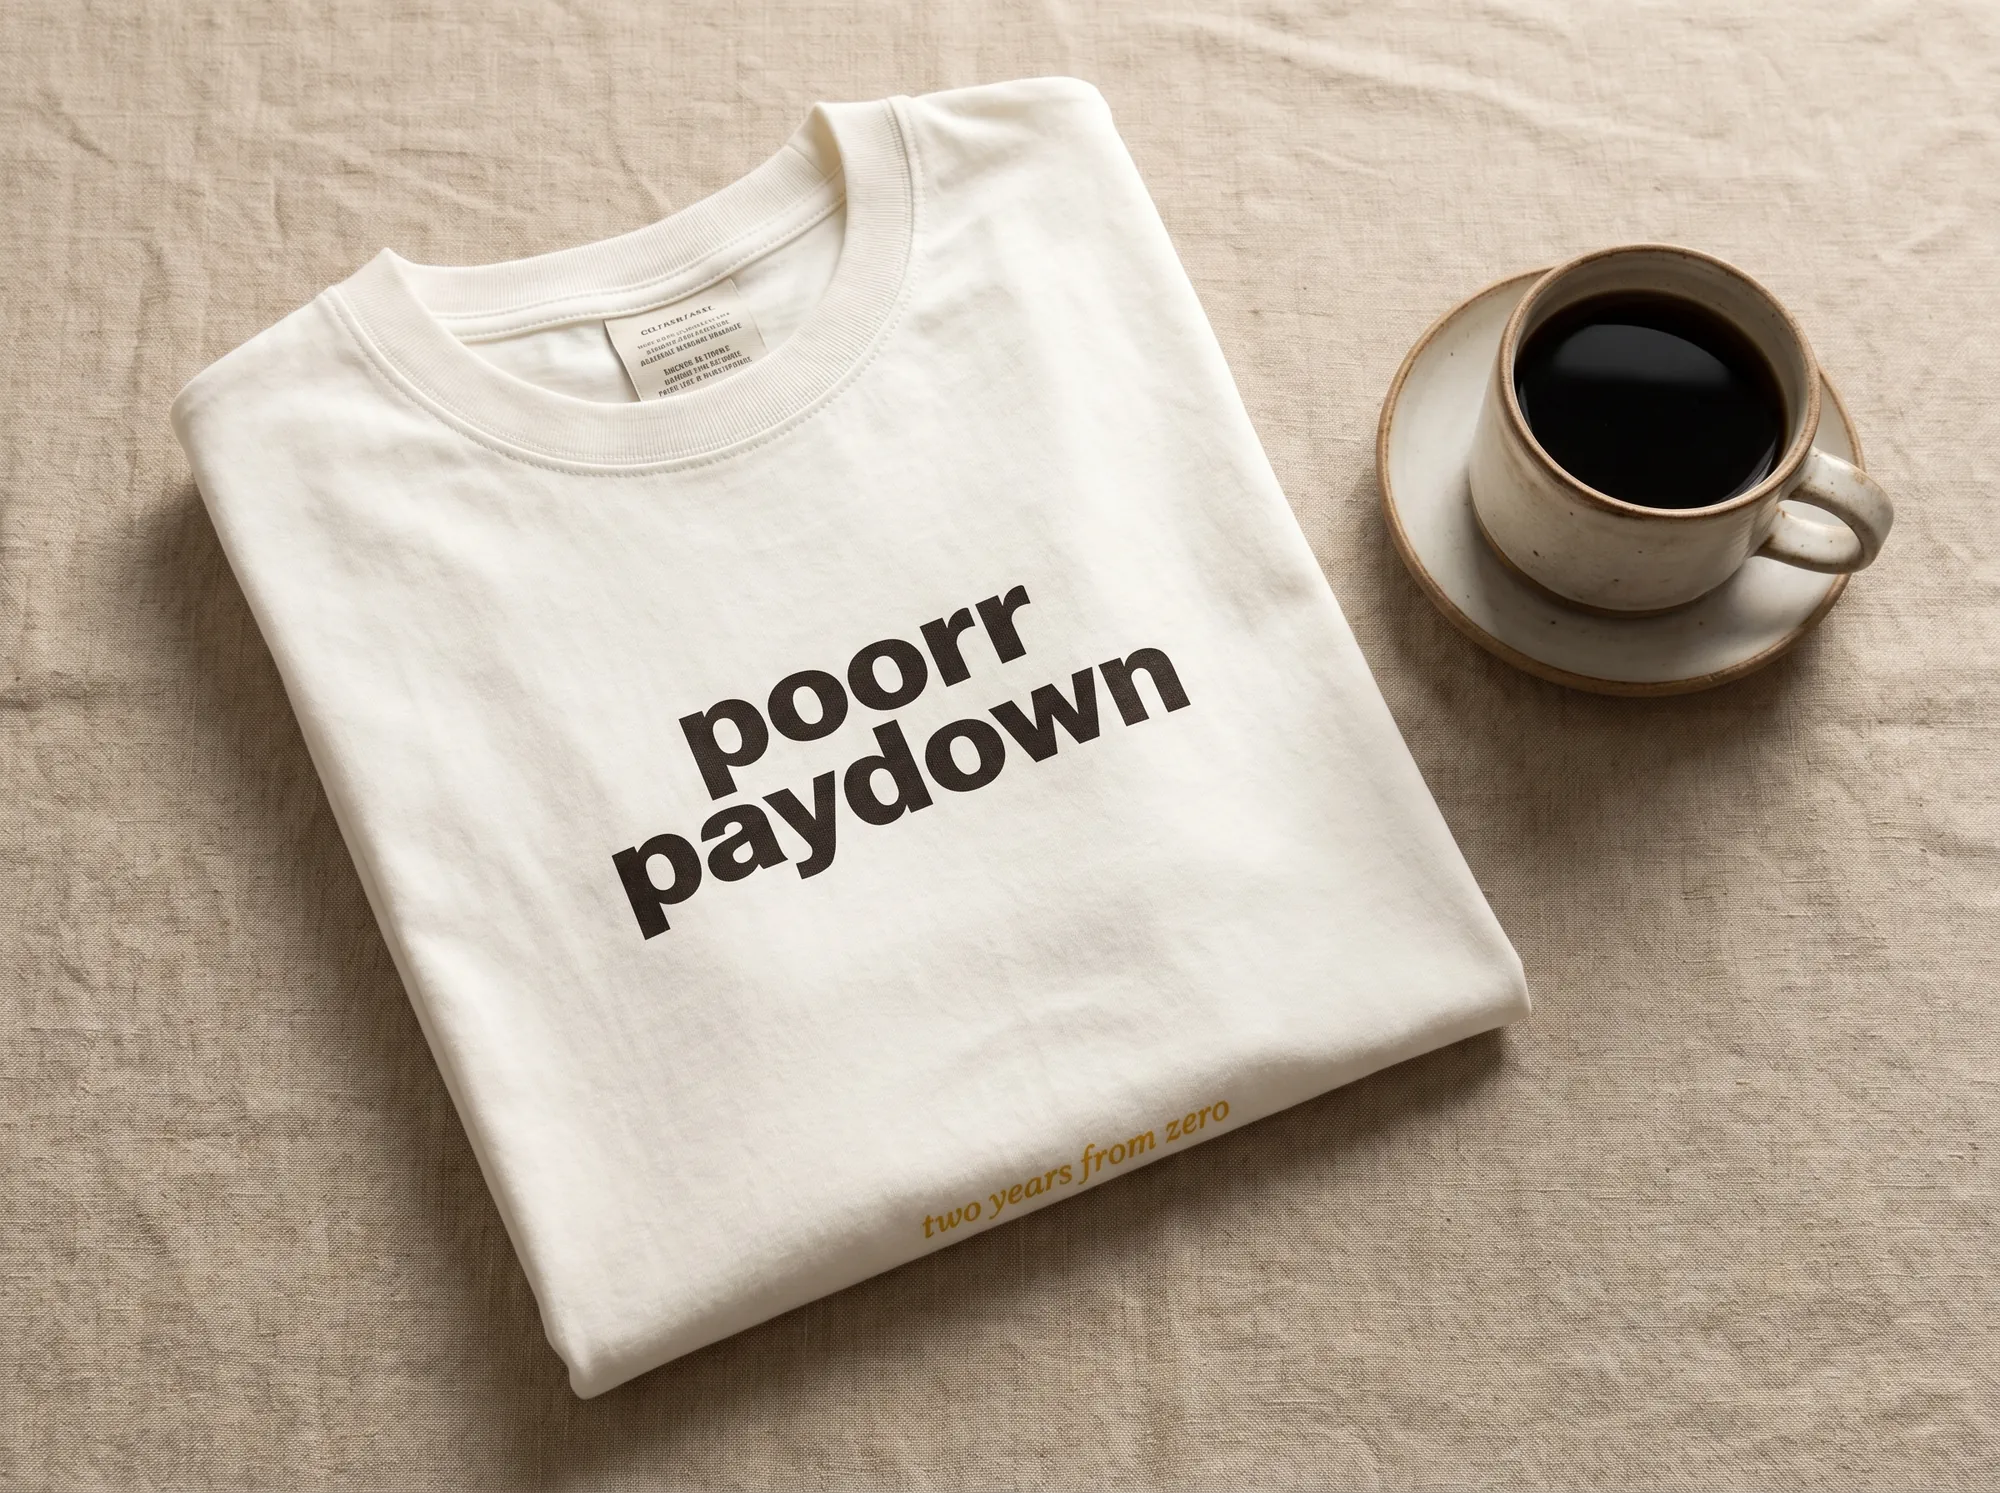
Apparel
Poorr Paydown Tee
A heavyweight cream cotton tee with the wordmark in warm charcoal and a small Lora italic line at the hem reading 'two years from zero.' For Paydown subscribers.
$32
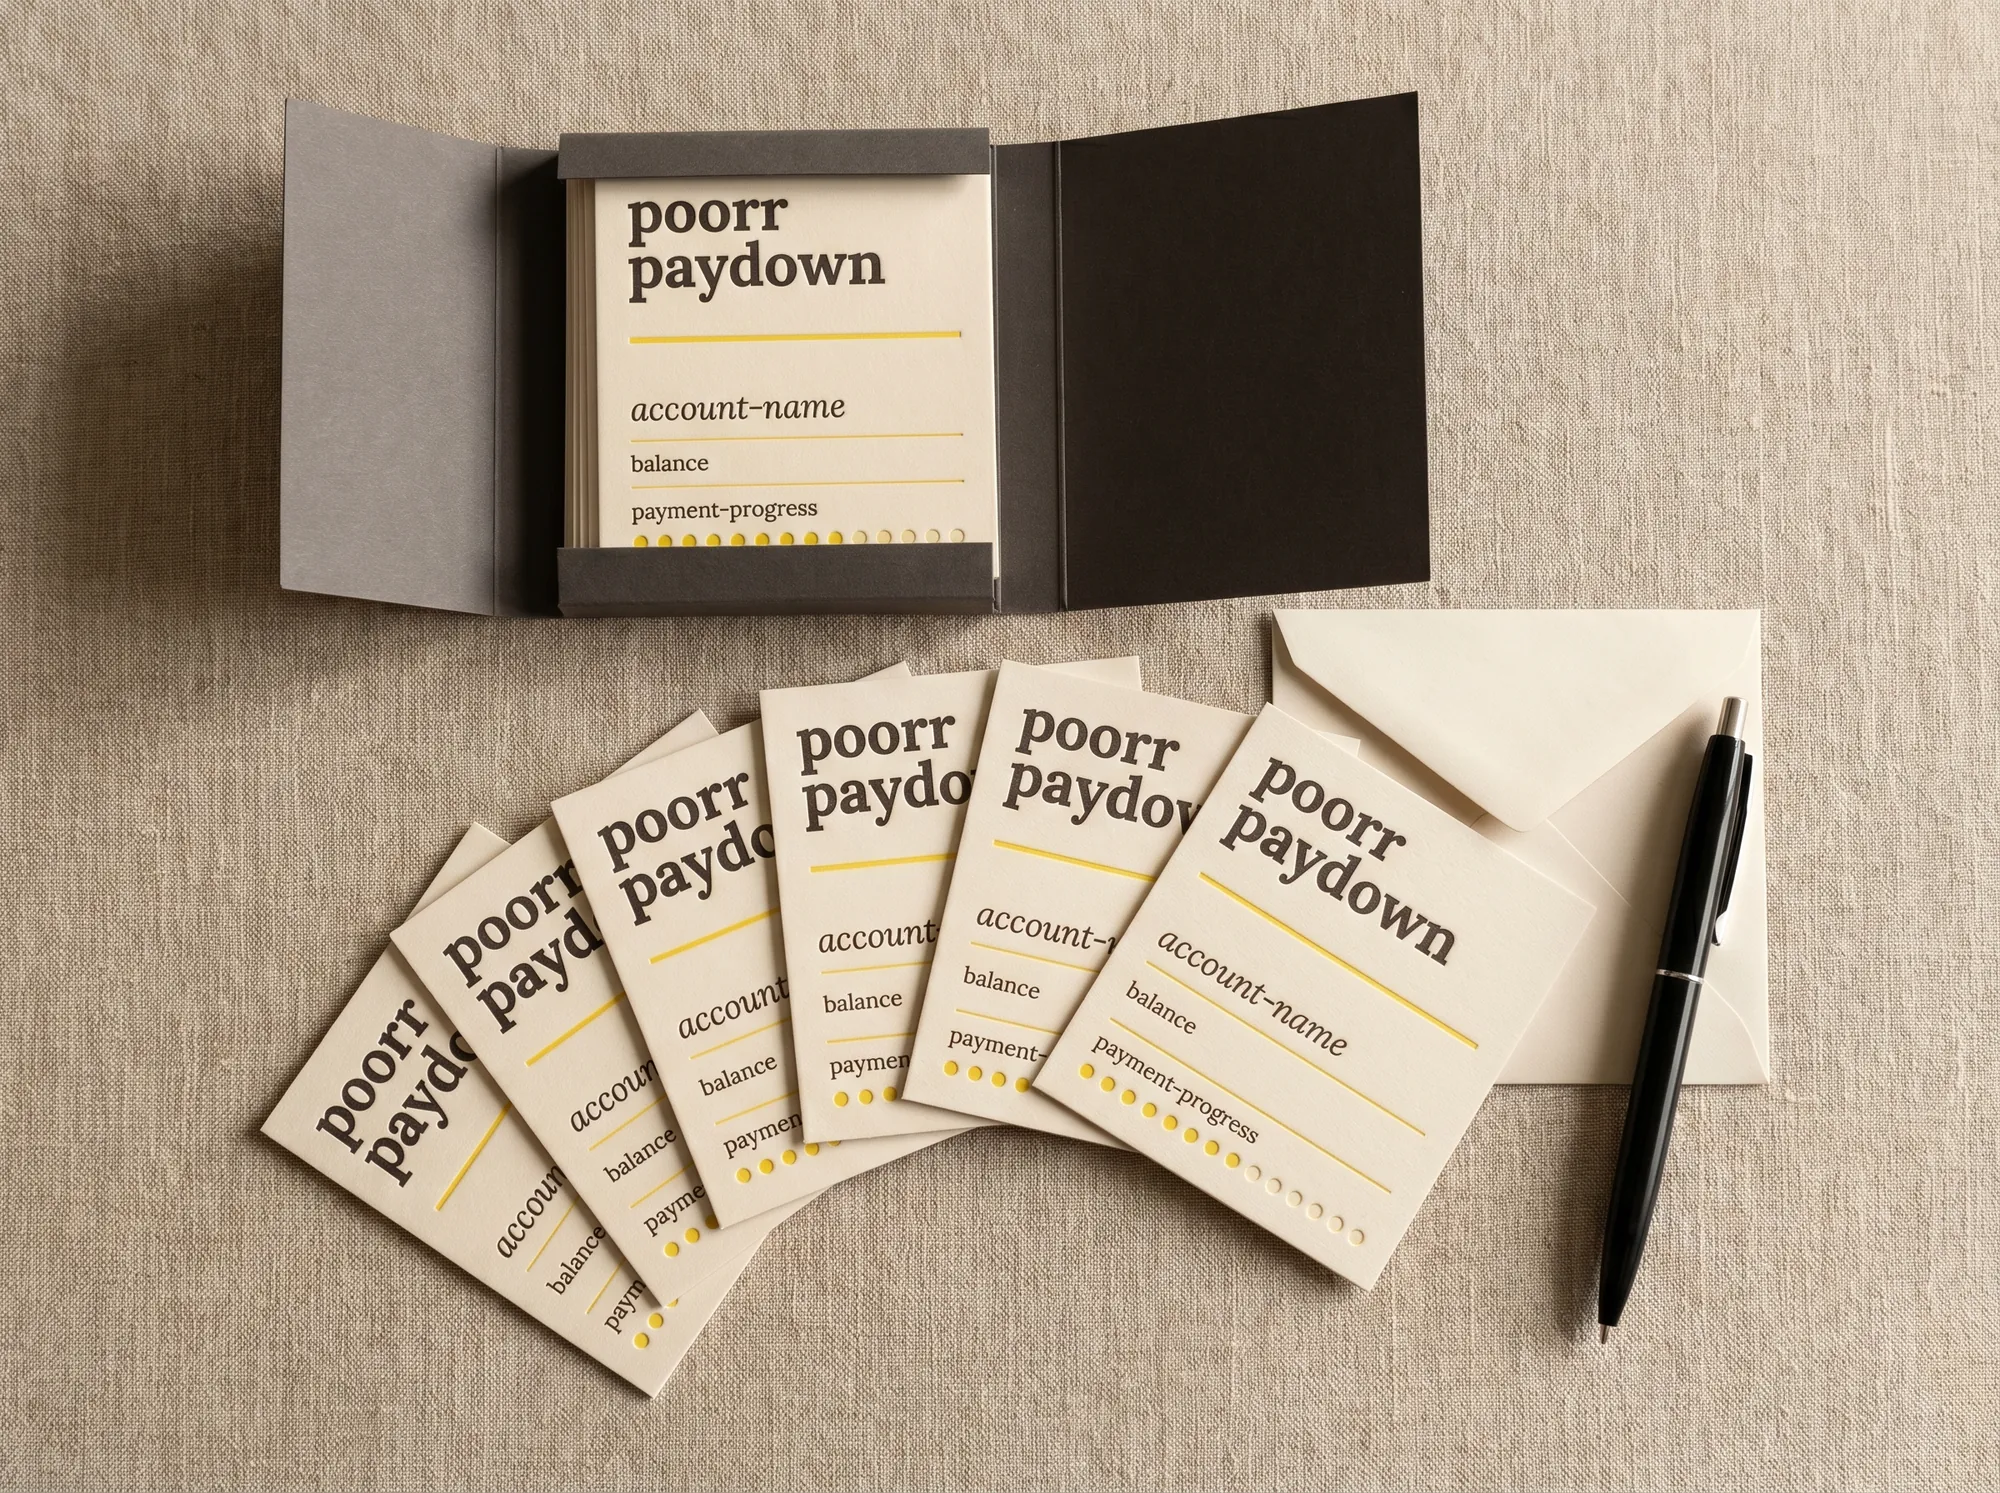
Stationery
Poorr Paydown Card Set
A flat case of fifty letterpress paydown-tracker cards — wordmark, account-name line, balance row, citrus payment-progress dots.
$24 per set
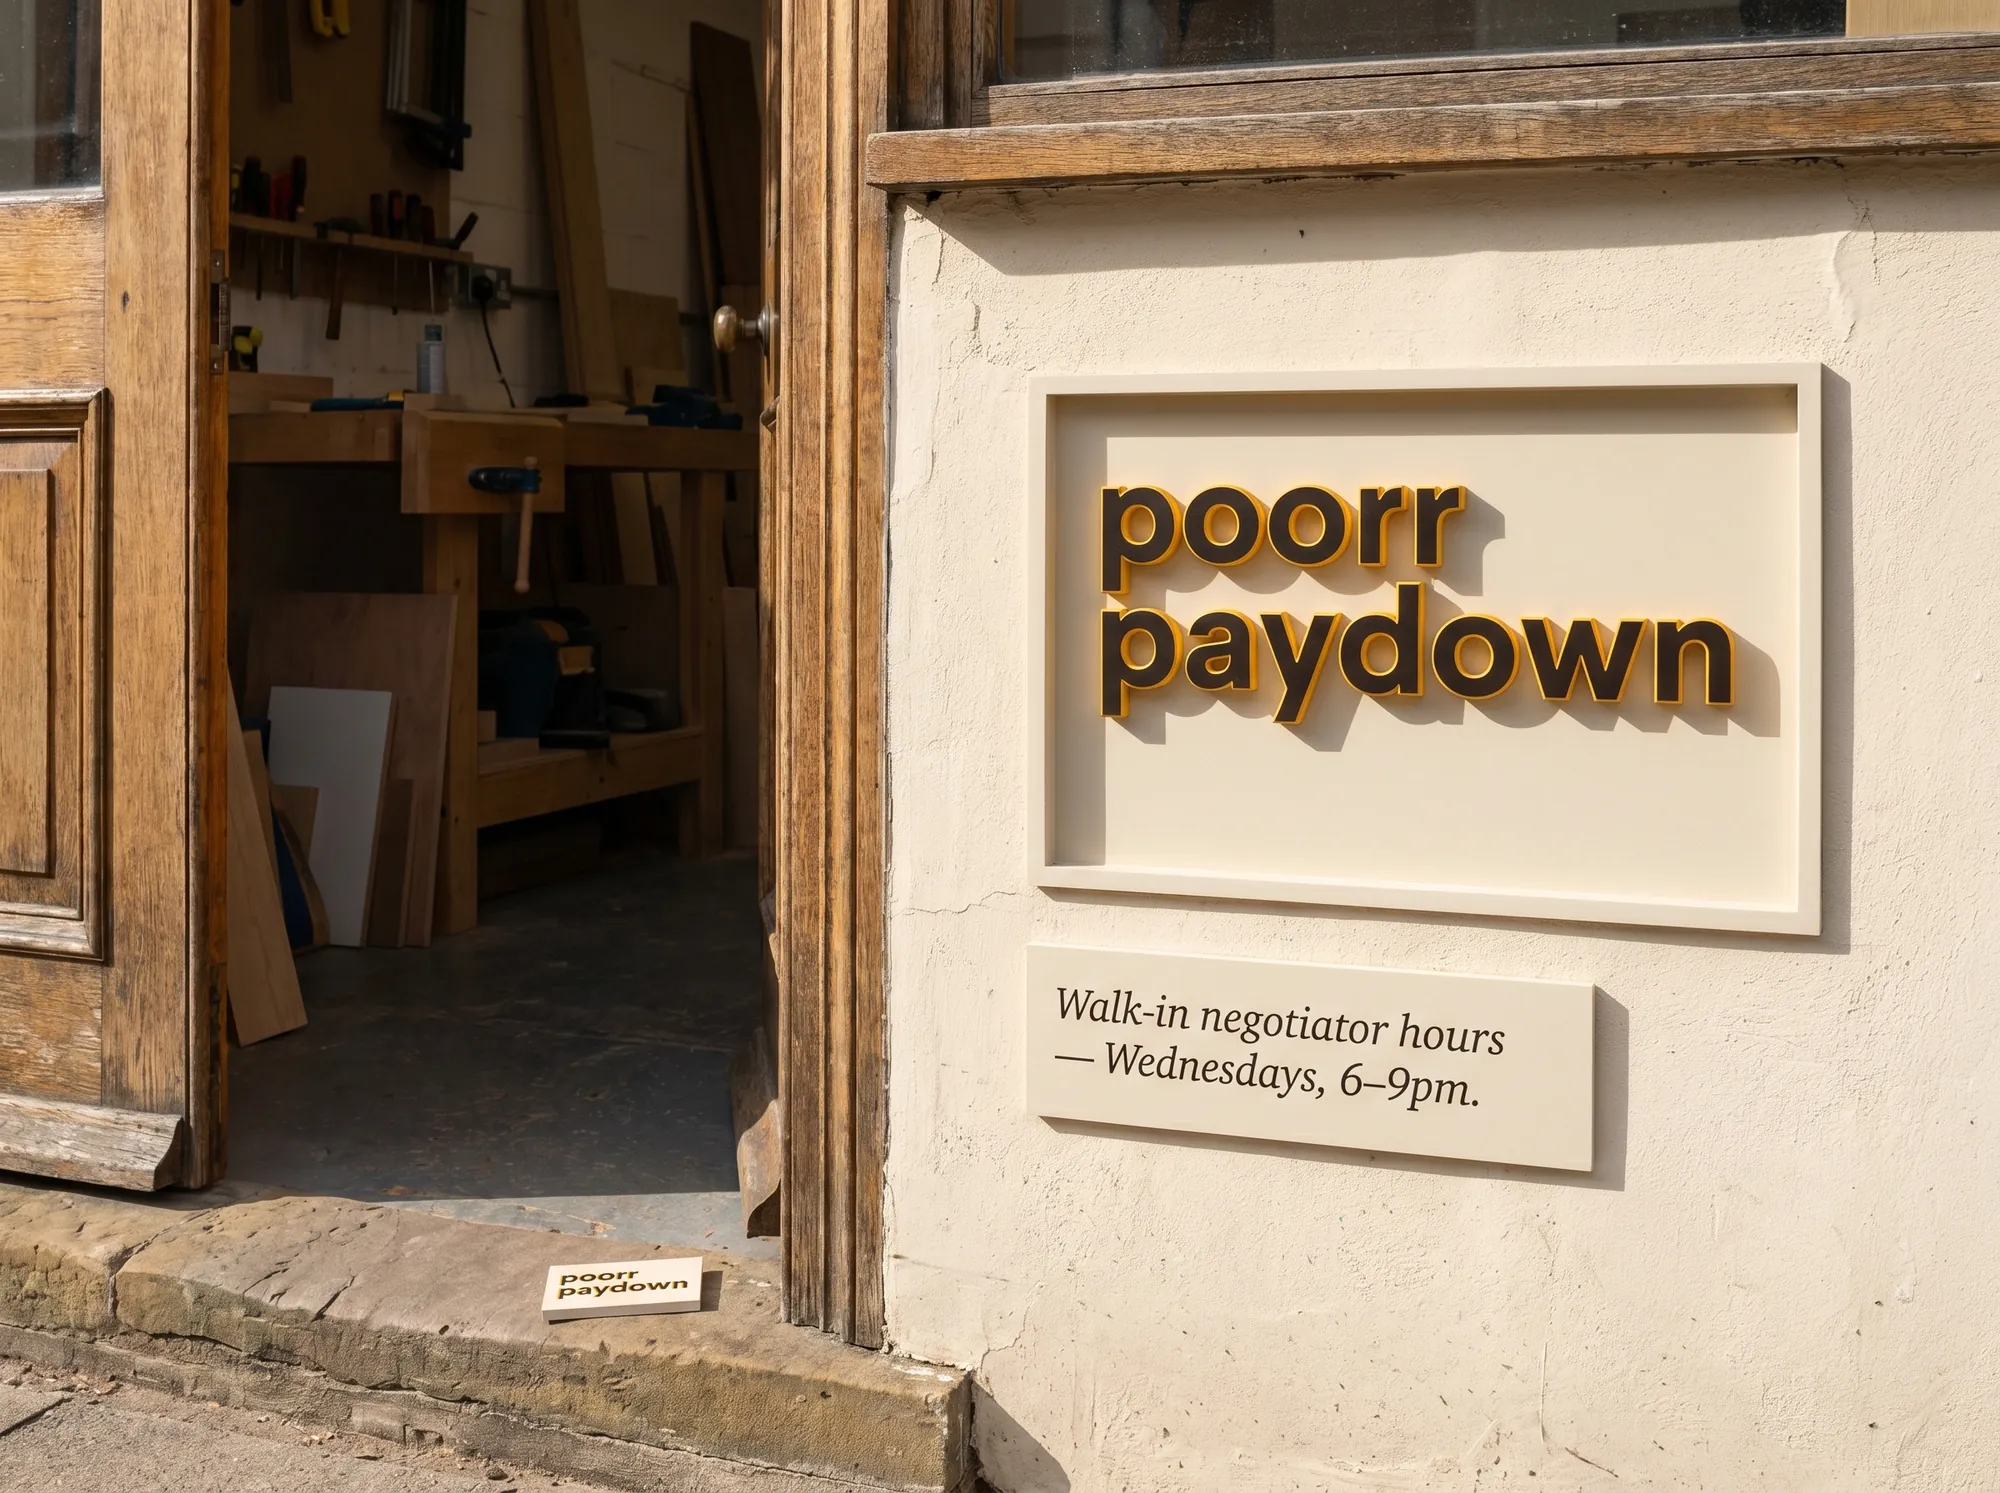
Signage
Poorr Paydown Office Plate
The painted-MDF wordmark plate that hangs at the Poorr workshop space during Paydown office hours — working public signage marking the office-hour window.
Internal use
Radio Ad Script
Thirty seconds of Poorr in this vertical. Visitors often play it twice — and every listen makes the brand a little more familiar in their head. That familiarity belongs to the owner.
“Old way: four credit cards, four minimums, no plan, a lot of shame. New way: one payoff timeline, one monthly number, no moralizing. Poorr — a debt paydown tool that treats you like an adult. Poorr dot com.”
For the investor
Debt Paydown is one of 10 directions.
Every Poorr industry is an application of the same one-word thesis: the not-yet-rich audience is enormous, under-branded, and ready for a consumer brand that treats them as adults. You do not have to pick one vertical to own the domain. The ten industries in this package are a menu; the audience is the asset. While you choose, the editorial keeps ranking and the brand keeps compounding.